Excel Stress-Testing Model
تفاصيل العمل
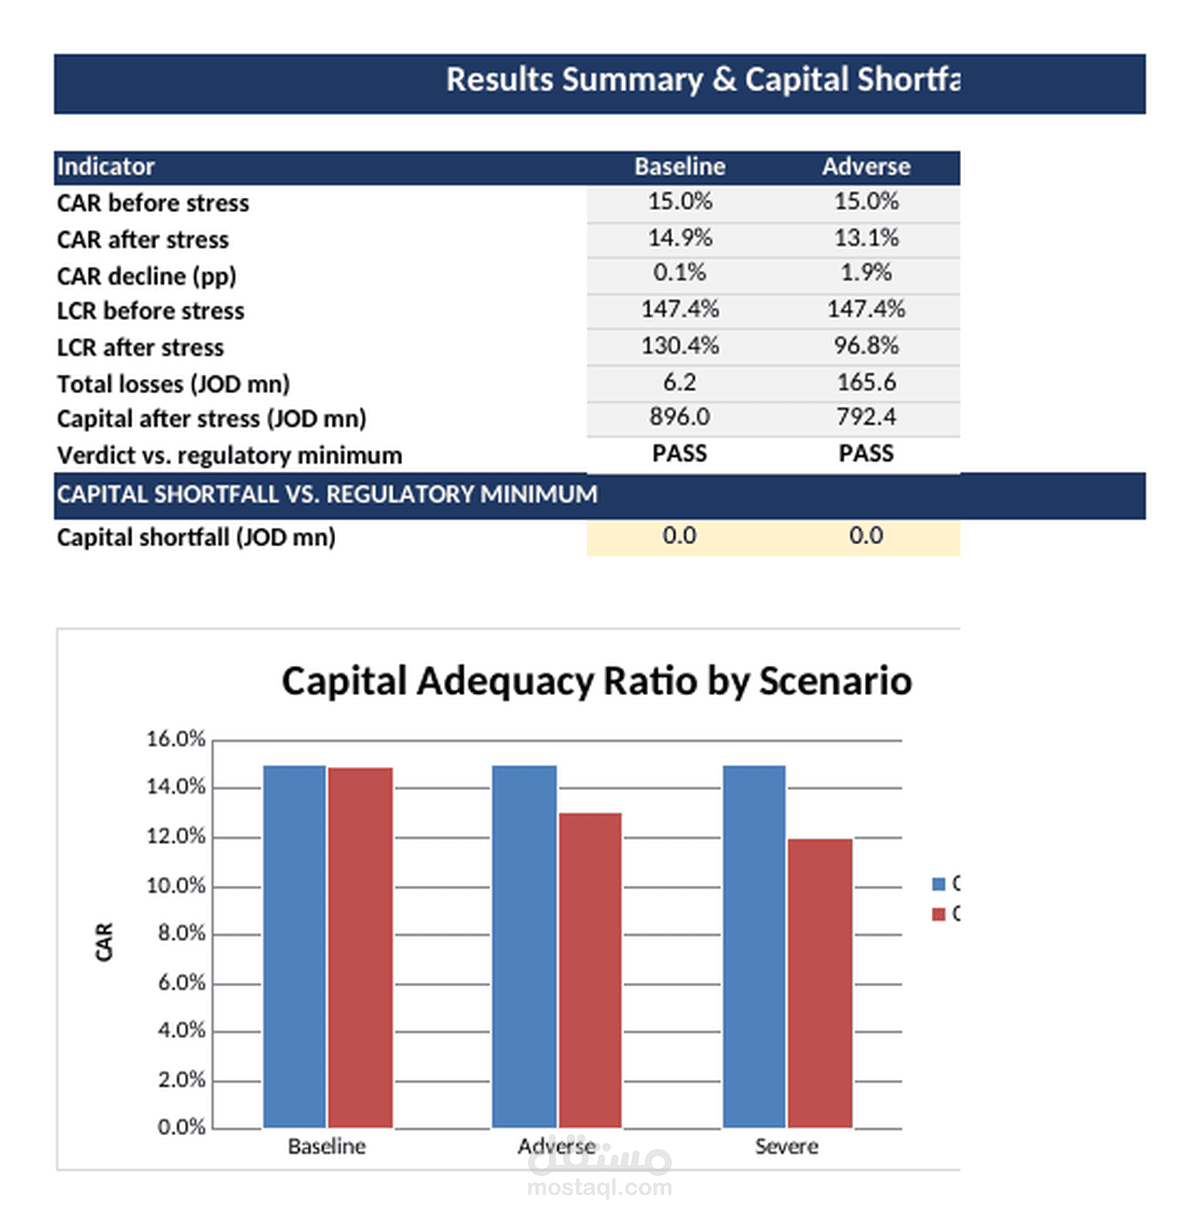
Description: A fully formula-driven, Basel III-aligned macroprudential stress-testing workbook for a representative commercial bank — no hardcoded results; every output is a live formula you can trace and audit.
Structure (8 sheets): - Cover — executive summary with headline outputs - Inputs — bank balance sheet and assumptions (blue = editable inputs, per banking-model convention) - Scenarios — Baseline / Adverse / Severe macro shocks, calibrated to Jordan’s history and IMF forecasts - Engine — credit losses (Loans × ΔNPL × LGD), bond revaluation via duration, post-tax capital impact, RWA migration, deposit run-offs and LCR - Results — scenario verdicts vs. the regulatory minimum and capital shortfall in JOD - Sensitivity — two-way grid (8 NPL shocks × 7 LGD levels) with conditional color formatting - Historical Data — actual Jordanian indicators (World Bank / IMF), 2015–2024, with charts - Sources — full data references
Under the severe scenario, CAR falls from 15.0% to 12.0% and LCR from 147% to 75% — demonstrating how the model surfaces binding constraints.
Tools: Advanced Excel (formulas, charts, conditional formatting, scenario architecture)