Credit Risk Pricing Model for Digital Lending Using Machine Learning and Predictive Analytics
تفاصيل العمل
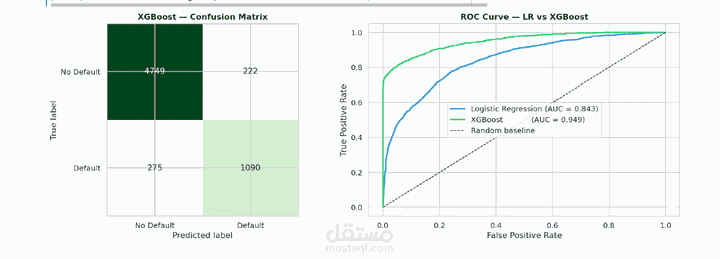
Developed an AI powered credit risk pricing model for digital lending platforms using machine learning and predictive analytics to improve loan approval decisions and minimize portfolio losses. The project analyzed over 31,000 loan applications, performed comprehensive data cleaning, feature engineering, and model validation, then compared Logistic Regression with XGBoost for default prediction.
The solution incorporated SHAP explainability to provide transparent and interpretable AI decisions, enabling risk based pricing while supporting regulatory compliance. Results demonstrated that XGBoost significantly outperformed the baseline model in predictive performance, reducing expected credit losses and improving lending profitability through more accurate borrower risk assessment.